Farmers Branch, TX
Trucking Insurance in Farmers Branch With One Agent on Your File
We write commercial trucking insurance for owner-operators, new-authority carriers and small fleets. That means primary liability, physical damage, cargo coverage, bobtail and trailer interchange, plus hotshot, box truck and dump truck policies. Carriers from Farmers Branch, Carrollton and Irving work with the same person on their file from quote to renewal.
- In business 5 years
- Same agent start to finish
- Quotes by phone or video
- Filings and certificates handled
Why Carriers Stay With a Small Office
Big call centers hand you to whoever picks up. Here, the person who quotes your trucks is the person who answers when a broker needs a certificate.
- One person knows your file
- The agent who takes your first call stays on your account. You don't explain your lanes, your drivers or your loss history twice. When something changes mid-term, you call someone who already knows the truck.
- Five years on trucking accounts
- Our office is in business 5 years now. We've watched how underwriters treat new authorities, out-of-radius runs and drivers with a ticket or two. You hear from us early how your file is likely to be read.
- Plain answers on what you're buying
- We go through limits, deductibles and exclusions line by line before you sign. If a cargo form excludes a commodity you haul, you hear it from us first, not after a claim.
- Paperwork that holds up
- We submit the proof of liability that FMCSA needs for your authority to stay active. When a shipper or broker asks for proof of coverage, we make sure their exact name and required limits appear on it. One wrong line can lose you a load, so every certificate gets a second look before we send it.
- Office, phone or video
- Come by the office, call, or sit down with us on a video call. Most of our clients never need to leave the cab to get a policy in place.
Coverage for the Way You Haul
We have been in business 5 years, and trucking is all we write. Most of our clients run one to a dozen trucks, so we build each policy around what you actually haul and how far you go. Start with primary auto liability and add physical damage, motor truck cargo, non-trucking liability or trailer interchange as your contracts call for them. We also have pages on owner-operator, new authority, fleet, hotshot, box truck, and dump truck and construction truck insurance.
Commercial Trucking Insurance
The full policy package a motor carrier needs to run legally and get loads, built around your trucks, drivers and freight.
Primary Auto Liability
The liability coverage your MC authority depends on, with the filings and certificates handled by the same person who wrote your quote.
Physical Damage
Collision and comprehensive coverage that pays to fix or replace your tractor, straight truck or trailer after a wreck, theft, fire or hail.
Motor Truck Cargo Insurance
Cargo coverage built around your commodities, limits and broker contracts, so a lost or damaged load does not come out of your pocket.
Non-Trucking Liability (Bobtail)
Liability coverage for leased owner-operators when the truck is off dispatch, matched to what your motor carrier's lease asks for.
Trailer Interchange Insurance
Physical damage coverage for trailers you haul under a written interchange agreement, matched to the limit your contract or the rail yard asks for.
Owner-Operator Truck Insurance
Coverage for one-truck operators, whether you run under a carrier's lease or your own MC authority, with one person handling it from quote to certificates.
New Authority Truck Insurance
Coverage and federal filings for carriers with a brand-new MC number, set up by one person who stays on your file through activation.
Fleet Truck Insurance
Coverage for a growing fleet on one policy, with trucks, drivers, filings and certificates kept current by the same people all year.
Dump Truck Insurance
Liability, physical damage and job-site certificates for dump trucks, mixers and other construction haulers, set up by one person who knows your file.
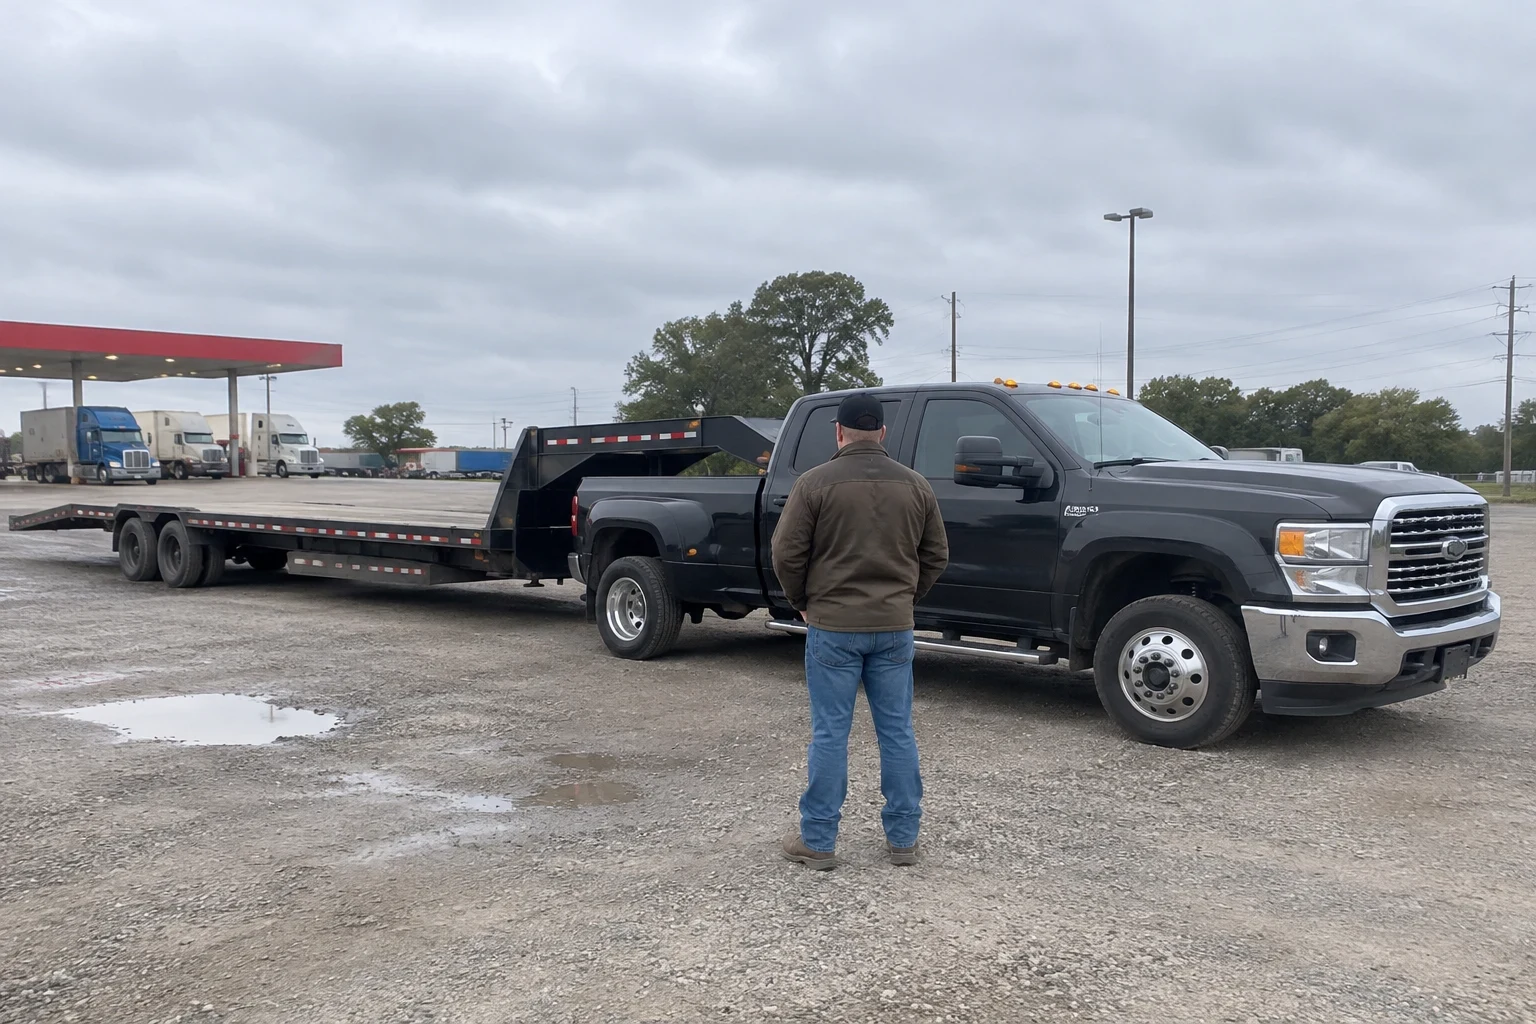
Hotshot Truck Insurance
Coverage for one-ton and medium-duty pickups pulling flatbed or gooseneck trailers, with the right filings and cargo limits for what you haul.
Box Truck Insurance
Liability, cargo and physical damage coverage for straight trucks and box trucks, set up to match the loads you haul and the contracts you sign.
What Moves Your Premium
No two trucking quotes come out the same, even for the same truck. Underwriters price risk, and a handful of things carry most of the weight. Here is what we look at with you before any number comes back.
We gather your details on the phone, then come back with a written quote that shows each coverage and its premium separately. Nothing is bound until you have read it and said yes.
- Driver records
- MVRs for every driver on the policy matter more than almost anything else. Years of CDL experience count too. A new driver with a clean record can still price higher than a seasoned one with a minor ticket.
- Age of your authority
- Underwriters can't judge an MC number that was issued last month, so year one tends to carry a higher premium. Once you have a year or two of claim-free loss runs to show, renewal often brings more carriers to the table.
- What you haul and how far
- Dry van freight, steel, aggregate and reefer loads all rate differently. A local dump truck running a short radius is a different risk than a hotshot running coast to coast.
- What the equipment is worth
- The value you put on each tractor and trailer drives the physical damage premium. A newer rig costs more to cover than an older one you own outright. If a lender holds the title, it often sets the highest deductible you're allowed to carry.
- Limits and deductibles
- Higher liability limits and lower deductibles raise the premium. Shipper and broker contracts often dictate the limits, so we start from what your contracts require.
- Loss history
- Past claims follow your operation. We pull loss runs early so there are no surprises when the underwriter looks.
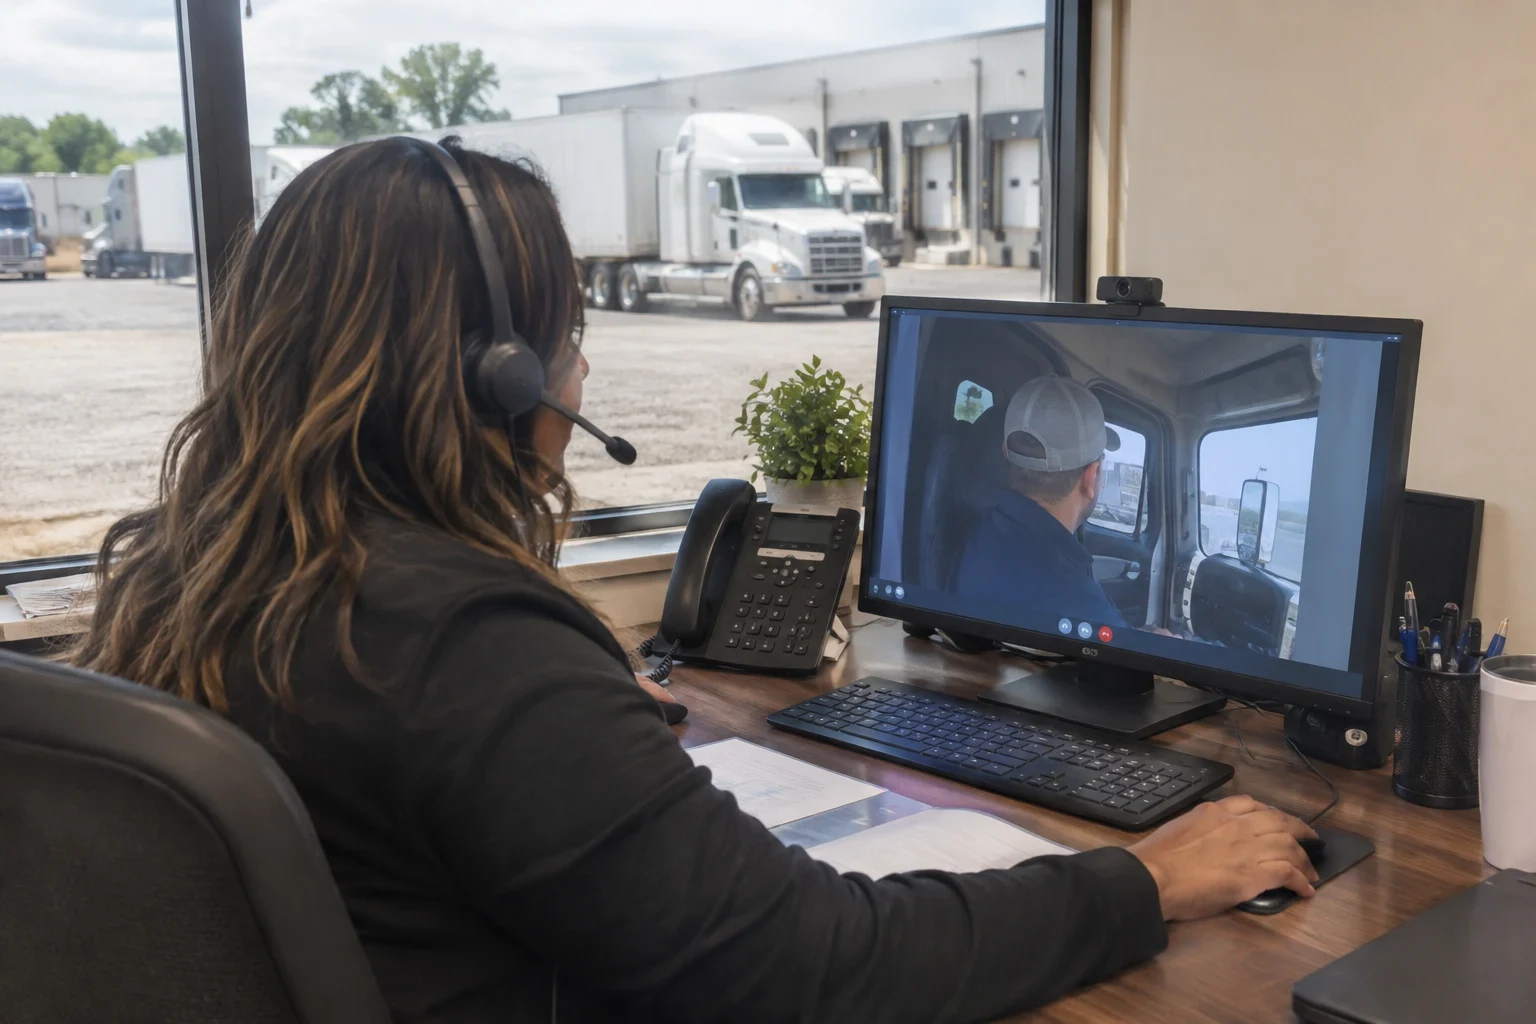
A Trucking Insurance Office in Farmers Branch
Our office is in Farmers Branch, and we write insurance for trucks and nothing else. We work with owner-operators, carriers getting their first authority and fleets that run anywhere from a couple of units to a few dozen. Hotshot drivers, box truck operators and dump truck outfits on construction jobs make up a good share of our book too.
We stay small so each client gets one person who knows their account. That person answers the phone when a broker needs a certificate on short notice, and knows your trucks when a claim comes in. We would rather handle fewer accounts well than run you through a queue.
We don't oversell. If you only need primary liability and cargo to start, that is what we quote. As your operation grows, we add coverage when your work actually calls for it.
- In business
- In business 5 years
Carriers We Work With Around the Metroplex
Our office is in Farmers Branch, and we write policies for carriers across the north side of the metroplex. That includes Carrollton, Addison, Coppell, Irving, Lewisville, Plano and Richardson, plus Euless, University Park and Highland Park. Since we work by phone and video, your yard doesn't need to be next door.
- Farmers Branch
- Carrollton
- Addison
- Irving
- Coppell
- University Park
- Highland Park
- Plano
- Lewisville
- Richardson
- Euless
Your policy follows your trucks wherever your authority lets you run. Where you garage the trucks still affects the rate, so we ask about it on the first call.
How Getting Covered Works
It is the same handful of steps for a single owner-operator or a ten-truck fleet. The same agent handles each one.
- 1
Start with a phone call
Tell us about your operation: what you haul, where you run, and what your contracts require. Have your DOT number, MC number if you have one, and your VINs handy.
- 2
We gather the paperwork
We will ask for a driver list with CDL numbers, any loss runs from a prior policy, and lienholder information if a truck is financed. When a piece is still outstanding, we name the document and explain how the underwriter will use it.
- 3
Review the quote together
We walk you through limits, deductibles and what is excluded. If a coverage isn't needed for your work, we say so and leave it off.
- 4
Bind, file and get you rolling
Once you say yes, we bind the policy and handle the required filings. Give us the list of brokers and shippers who want proof of coverage, and we get a certificate out to each of them.
- 5
Same agent after the sale
Adding a truck, dropping a driver or picking up a new contract means one call to the person who set up your policy. We check in ahead of renewal too.
Questions Truckers Ask Us
How much is trucking insurance going to cost me?
It depends on your drivers, what you haul, how far you run, your truck values and how long you have had your authority. We can't give an honest number until we have those details. Once we do, you get a written quote with each coverage priced on its own line.
Can I get coverage with a brand-new MC authority?
You can. Carriers just starting out are some of the clients we work with most. The first year usually runs higher than later years, since underwriters have no loss history to go on. We get your filings lined up so your authority can go active.
What filings do I need?
Interstate carriers need proof of liability coverage filed with FMCSA under their DOT and MC numbers. Carriers running intrastate in Texas also need a filing with the state. We handle the filings once your policy is bound and confirm they went through.
What is the difference between bobtail and non-trucking liability?
People use the names loosely, but they are not always the same form. Non-trucking liability usually covers an owner-operator leased to a motor carrier when driving for personal use, not under dispatch. We go over the policy language with you, so you can tell where your coverage stops and the motor carrier's policy picks up.
A broker wants proof of coverage before I take the load. What do I do?
Phone the agent who wrote your policy and tell us which broker it is and what they want shown. Before the certificate goes out, we compare the limits and wording to that broker's list so it isn't kicked back.
Will I deal with someone new every time I call?
No. The agent who quotes your trucks stays on your account for changes, certificates, claims questions and renewals. That is the main reason clients stay with us.
Do I have to come into the office?
No. You are welcome to stop by, but most clients handle everything by phone or on a video call. We can review documents with you on screen.
Talk to the Agent Who Will Keep Your File
Tell us about your trucks and your work, and we will put together a quote that fits what you haul. The person you talk to is the one you will keep.