ServicesHotshot Truck Insurance
Hotshot Truck Insurance in Farmers Branch
You run a dually and a gooseneck, not a semi, and your policy should be built that way. We set up liability, cargo and physical damage for hotshot rigs, file what your authority needs and keep the same person on your account.
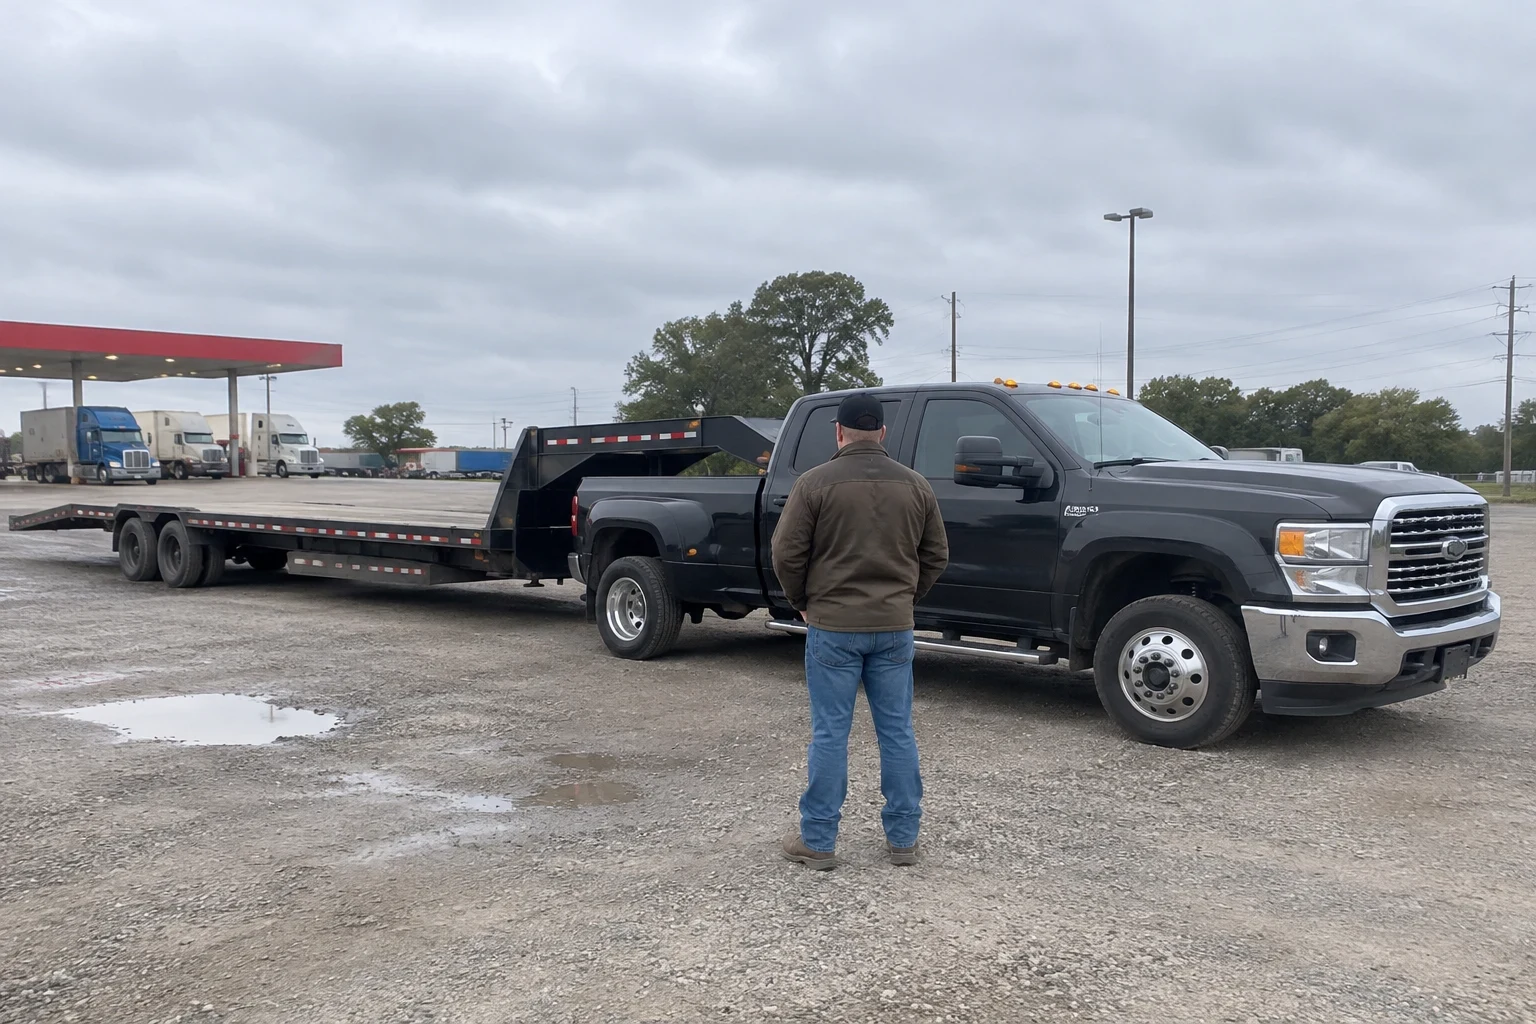
Insurance for the dually-and-gooseneck crowd
A hotshot rig doesn't look like a semi, but the rules can treat it like one. Your truck might be an F-450 or Ram 3500. Once the truck and trailer together go over 10,001 pounds and you're hauling for pay, you're a motor carrier with a DOT number, and in many cases MC authority too. Your coverage needs to reflect that, even if the rig looks like something a contractor parks at a job site.
Our office is small on purpose. Whoever quotes your truck also sends your filings, issues certificates of insurance and calls you ahead of renewal. When a broker wants paperwork, you're talking to someone who already knows your file.
Hotshot drivers around Farmers Branch pull all kinds of things, from equipment and machinery to pipe and vehicles. We start by asking what you haul and where you take it, then build the coverage around that.
What goes into a hotshot policy
- Primary auto liability
- Covers the other driver's injuries and property if a wreck is your fault. For-hire carriers running interstate need federal filings tied to this coverage, and we send them.
- Motor truck cargo
- Protects the load you're carrying. We set the limit by what you normally haul and read the exclusions closely, because some forms restrict vehicles, heavy machinery or high-value gear.
- Physical damage for truck and trailer
- Collision and comprehensive on your pickup, with the gooseneck or flatbed scheduled separately so it's protected as well. You choose deductibles that fit your cash on hand.
- Filings and certificates
- We handle the federal and Texas filings your authority requires. If a shipper or broker asks for a certificate of insurance, one call and we get it out.
- Bobtail coverage
- Leased drivers are often covered by the carrier only while under dispatch. The Non-Trucking Liability (Bobtail) Insurance page walks through the gap when you're driving off the clock.
Signs your current setup doesn't fit
You're on a personal or small business auto policy
Those policies usually exclude hauling for hire. A claim on a paid load could be denied.
Brokers keep rejecting your certificate
Load boards and brokers often want higher cargo limits than the minimum. If you're losing loads over paperwork, the policy needs another look.
Your trailer isn't listed
A lot of hotshot drivers find out after a wreck that the gooseneck was never scheduled. Check your declarations page for the trailer's VIN.
You changed what you haul
Moving from farm equipment to cars or oilfield pipe can change your cargo terms. Tell your agent before the first load, not after.
You crossed state lines for the first time
Going interstate brings federal filings and higher liability minimums. Running without them can put your authority at risk.
What sets the price on a hotshot policy
Put two hotshot drivers in identical trucks and their premiums can still land far apart. The underwriter is guessing at the odds of a claim and what it might cost to pay out. We can't give you a number until we have your details, but these are the pieces that carry the most weight.
Your driving record
A clean MVR backed by a few years of commercial miles helps a lot. Fresh tickets, at-fault wrecks or very little time behind the wheel raise the premium.
What rides on your deck
Equipment, vehicles and oilfield pipe get rated differently than general freight. Bumping your cargo limit higher because a broker asked for it adds cost too.
Your running radius
Short runs that stay inside Texas usually price lower than hauling through several states. More miles and more states put more risk on the policy.
Truck and trailer value
A late-model dually and gooseneck cost more to fix or replace, so physical damage goes up. Choosing a higher deductible can bring it back down some.
Time under your own authority
Insurers often charge more in the first year or two on a new MC number. Our New Authority Truck Insurance page covers what to expect during that stretch.
How we set up your hotshot coverage
- 1
A phone call about your operation
We ask about your truck, trailer, drivers, loads and the miles you run. Have your DOT number, VINs and driver's license info handy. You can also meet us at our office or over video.
- 2
Shopping the markets
Not every carrier writes hotshot risks. We go to the ones that do and compare the terms that matter for your loads, not just the premium.
- 3
Going over the quote with you
We walk through limits, deductibles and exclusions in plain words. If something you haul isn't covered, we say so up front.
- 4
Binding and filing
Once you pick a policy, we bind it, send the filings and get your certificate of insurance to whoever needs it.
- 5
Staying on your account
Add a truck, change a trailer or pick up a new broker, and you call the same person. We review it with you before renewal.
Hotshot coverage, answered
I run under another carrier's authority. Do I need a full hotshot policy of my own?
Most of the time, no. The carrier you're leased to usually carries the liability, and you may only need physical damage and bobtail. If you haul under your own MC number, you need the whole policy plus the filings that go with it. We sort out which side you're on during the first call.
Can my personal pickup policy cover paid loads?
Almost never. Personal auto policies leave out hauling for hire. Once someone pays you to move freight, you need commercial coverage.
Does staying under 26,000 pounds change my insurance?
It mostly changes your licensing, since a lot of hotshot rigs stay under that line so the driver doesn't need a CDL. The insurer still weighs your weight class, what you haul and how far you go. Send us the GVWR of the truck and the trailer rating so we quote the right setup.
Will a hotshot policy cover cars I haul?
That depends on the insurance company. Many cargo forms limit vehicles or exclude them outright. If you pull cars, tell us up front so we place you with a company that will cover them.
How quickly can I get a certificate to a broker?
Once the policy is bound, you call and we send the certificate where it needs to go. The same person handles your file the whole way, so nobody has to start from scratch to figure out who you are.
Talk through your rig with us
Tell us what you drive, what you pull and where you run. We'll tell you what coverage fits and what it takes to get your filings in place.