ServicesPhysical Damage
Physical Damage Insurance in Farmers Branch
Liability pays for the other guy. Physical damage pays for your truck. We set the stated value, the deductible and the loss payee with you, and the same person who quotes your coverage handles your questions and claims later.
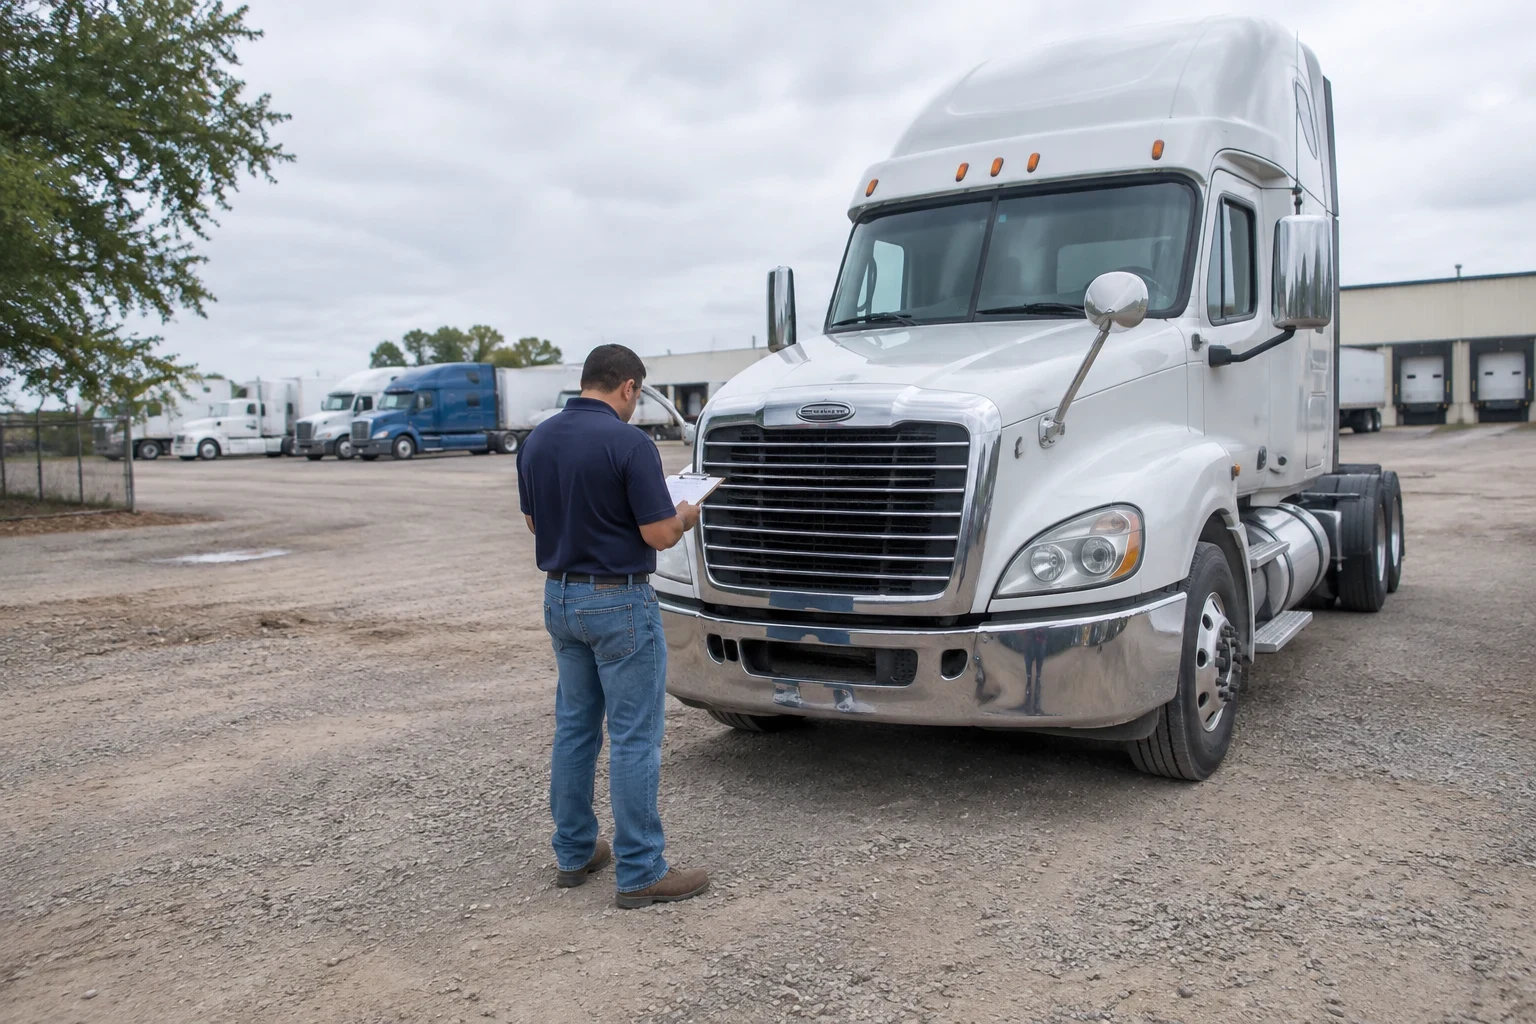
What Physical Damage Coverage Does
Physical damage insurance covers the truck itself. Collision pays when your unit hits something or rolls over. Comprehensive handles losses that are not a crash, like theft, fire, vandalism, falling objects and hail. Between the two, your truck gets fixed or replaced so you can get back to hauling.
No law requires it, and it is not part of your federal filings. Financed or leased trucks are another matter. Almost every lender and lessor writes it into the contract and wants their name listed as the party paid on a loss. Once the truck is yours free and clear, ask yourself one thing: if it were gone tomorrow, could you pay cash for the next one?
We are a small office. Whoever walks you through the stated value and deductible is the same person you call when you add a trailer, need a new certificate of insurance or have a claim.
What We Set Up on Your Policy
- 01
Collision coverage
If your unit runs into another vehicle, a guardrail or a loading dock, or tips over, collision handles the repair bill. Fault does not matter here. You pay your deductible and the policy picks up the rest.
- 02
Comprehensive or specified perils
Comprehensive covers theft, fire, vandalism, glass and weather. Some operators with older units go with specified perils instead, which covers a named list of causes for less premium. We explain what each one leaves out.
- 03
A stated value that matches the truck
Most trucks are written on a stated amount. Set it too high and you pay premium on value a claim would never return. Set it too low and a total loss pays out less than the truck was worth. We go over year, miles and condition with you to land on a fair figure.
- 04
Trailers and attached equipment
Your trailer can be listed with its own value. We also ask about permanently mounted items like sleepers, reefer units or custom equipment so nothing slips through.
- 05
Lender and lessor listing
When a bank or leasing company has money in the truck, we add them correctly so their paperwork goes through and your certificate of insurance shows exactly what they asked for.
- 06
Optional add-ons
Where the carrier offers them, we can price towing and downtime or rental reimbursement. You decide if they make sense for your operation.
Questions about Physical Damage?
Call(972) 736-5773When It Is Time to Review Your Physical Damage Coverage
A new truck loan or lease
Before the deal closes, the bank or leasing company will ask for proof of physical damage coverage with their name on it as loss payee. We can get that set up for you.
Your stated value has not changed in years
Trucks lose value, and sometimes the market swings the other way. An old number can mean you are overpaying, or coming up short on a total loss.
You run without it on a paid-off truck
Some owner-operators make that choice. Just know that one wreck or theft can take the truck and your income with it.
Storm season worries you
North Texas hail can total a truck parked in a yard overnight. Without comprehensive, that loss is yours.
You added a trailer or new unit
New equipment is not covered until it is on the schedule. Call before it goes out on a load.
How Getting Covered Works
- 1
Talk it through on the phone
We ask about your trucks, trailers, drivers and where the equipment is parked. If it is easier, we can meet at our office or over video.
- 2
Pin down values and deductibles
We go unit by unit to set the stated amount and talk through deductible options. A higher deductible lowers premium, but only if you could cover it after a loss.
- 3
Shop and compare
We take your information to the carriers that write your kind of operation and lay the quotes side by side, with what changes from one to the next.
- 4
Bind and send paperwork
Once you pick, we bind the policy and send certificates of insurance to your lender, lessor or shipper as needed.
- 5
Stay with you after
Same person, every time. If you add a truck, sell one or have a claim, you call the one who already knows your file.
What Moves Your Physical Damage Premium
Physical damage pricing mostly comes down to two things: what the truck is worth and the odds it gets damaged. We need to know your units and drivers before we can quote a number. These are the things the carriers weigh.
- Truck and trailer value
- The premium is a rate applied to the stated value. A newer, higher-value tractor costs more to cover than an older one.
- Deductible you choose
- A bigger deductible brings the premium down. We help you pick one you could really pay the week after a wreck.
- Driver record and experience
- Clean records and years behind the wheel work in your favor. Recent accidents or tickets push the rate up.
- Type of unit and work
- A dump truck on job sites, a hotshot rig and a box truck on city routes each carry different risk. Radius and where the truck is garaged matter too.
- Loss history
- Carriers look back several years at past physical damage claims, and those claims weigh on the price.
Physical Damage Questions We Hear
Is physical damage insurance required by the DOT?
No. Your federal and state filings deal with liability, not your own equipment. Physical damage becomes a must when a lender, lessor or motor carrier you lease onto puts it in the contract.
What happens if my truck is totaled?
Most truck policies pay whichever is lower: the stated amount or what the truck was really worth on the day of the loss. Your deductible is then taken out. That is why an honest stated value matters. If there is a loan, the lienholder is paid first.
I am leased onto a carrier. Doesn't their policy cover my truck?
Usually not. The carrier's policy covers liability while you are under dispatch. Your own truck typically needs its own physical damage coverage, and you may also want non-trucking liability for bobtail time.
Does physical damage cover the freight I'm hauling?
No. Freight falls under motor truck cargo insurance, which is a separate policy. We can quote both on the same call.
Is a trailer I pull under someone else's interchange agreement covered?
Not under your own physical damage policy. Non-owned trailers pulled under an interchange agreement need trailer interchange insurance. We will figure out which one fits your setup.
Ready to Put a Real Number on Your Truck
Give us your unit details and we will go through values, deductibles and options with you. You will deal with the same person from the first call to the last certificate.